Are There Food Delivery Wars Abroad? A Roujiamo Shop Owner’s Answer from Britain
This year marks my seventh year living in the UK. Six years ago, I opened a roujiamo shop in a small town in Exeter, which I named Rogamo — a name that is fast becoming the generic English term for roujiamo.
Before Rogamo, I had already been in the food and beverage business in China for ten years. When I opened my first shop in Beijing, group buying — the predecessor of food delivery — was just emerging in China. It was the era of the Hundred Groups War: every day, canvassers would walk into the shop, pushing us to join the group-buying platforms and luring both consumers and merchants with all manner of subsidies. Looking back, the Hundred Groups War was the precursor to the food delivery wars, and it was also where countless merchants first got drawn into the platform economy.
As an entrepreneur who entered the food and beverage industry in 2010, I can safely say I have been dealing with food delivery throughout my career, and I have watched every step of the way as delivery platforms shifted from parasitising the restaurant trade to gradually dominating it. Rogamo is now listed on delivery platforms as well, but food delivery in the UK is vastly different from food delivery in China.
This dynamic, comparative vantage point has made me realise that, after several rounds of subsidy wars, the domestic food delivery industry — platforms, merchants, and consumers alike — has forgotten that food delivery was originally nothing more than a simple delivery service that should follow the principle of “whoever benefits, pays”.
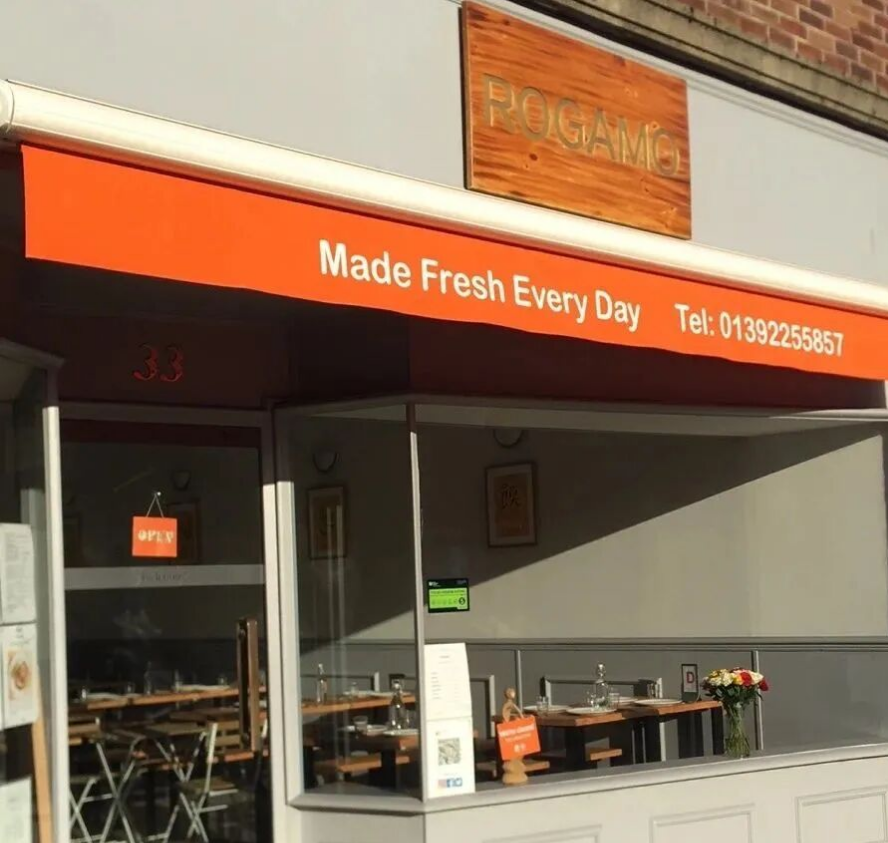
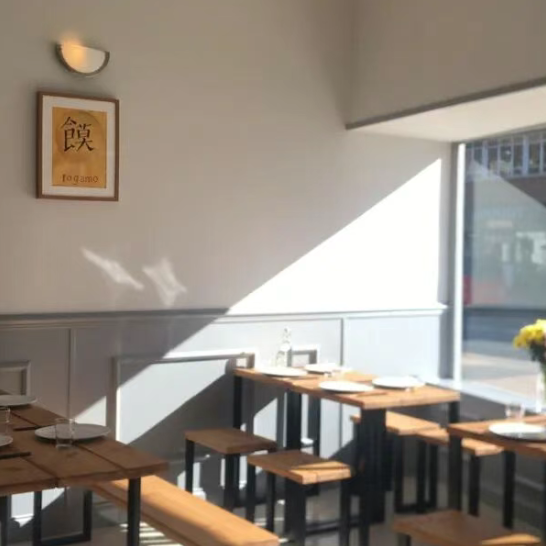
◉The Rogamo store.
What Is “Whoever Benefits, Pays”?
One afternoon last month, in the heart of Canary Wharf’s commercial district — peak food-delivery hours, you would think — my friend and I didn’t see a single delivery rider.
And in the small town where I live, the commercial district is home to plenty of chain restaurants — Asian chains like Wagamama and Pho, which have done a particularly good job of adapting their fusion offerings to local tastes. On a Sunday just over a fortnight ago, I went there for Vietnamese pho. Throughout my two-hour meal, I did not hear a single delivery-order alert go off in the restaurant, nor did I spot any delivery rider weaving through the streets of the commercial district.
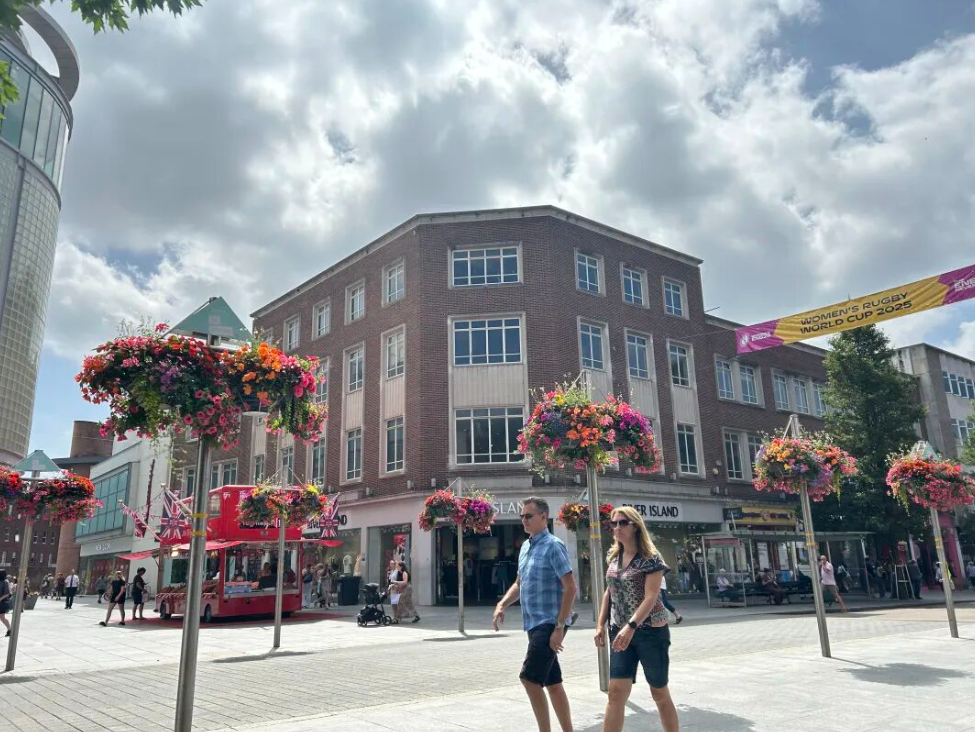
◉The main street of the small town where the Rogamo shop is located.
In other words, food delivery in the UK has not become so “developed” that traces of it permeate every street and alleyway at all hours, the way they do in China.
The main food delivery platforms in the UK are these four: Deliveroo, Uber Eats, Just Eat and Hungry Panda — all foreign companies.
Hungry Panda, known in Chinese as 熊猫外卖, was founded here in the UK by a Chinese international student. Judging by the orders at our shop, the vast majority of customers on the Hungry Panda platform are Chinese international students. Our storefront sits directly across from the apartment blocks where many of these students live, and delivery riders are always popping in to pick up orders — they park their vehicles right at our door, then walk the food to its destination on foot. Even so, the students still much prefer to order delivery to their apartments.
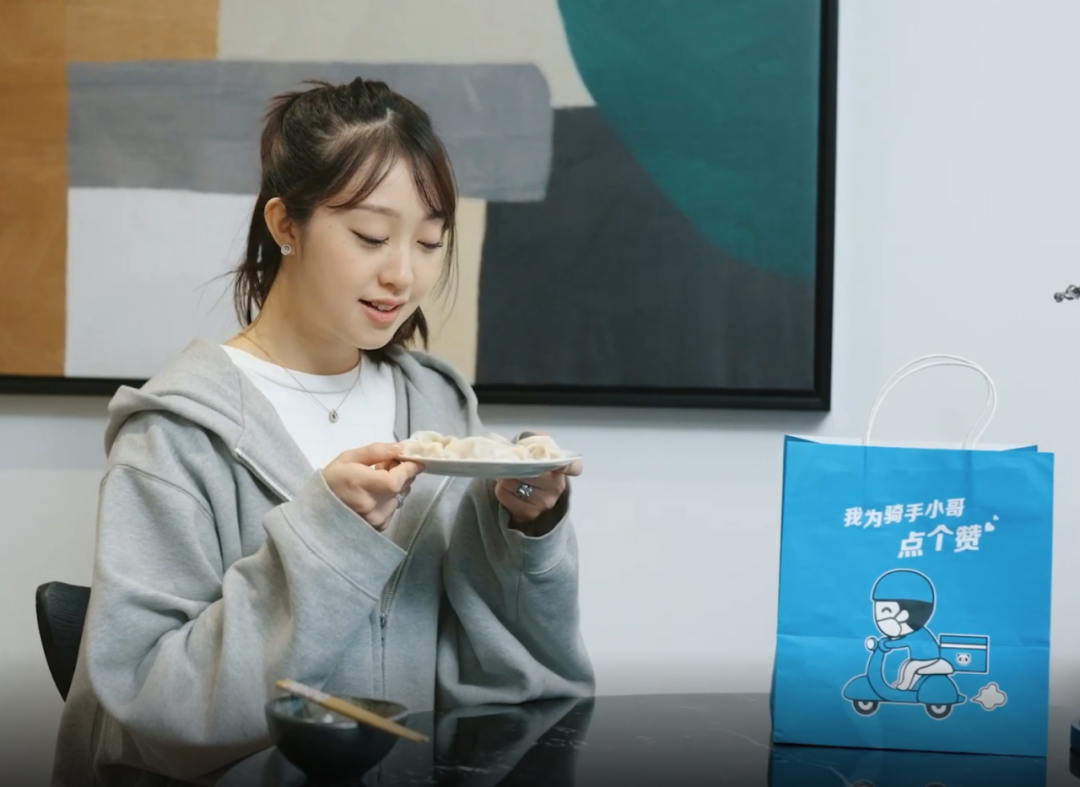
◉Hungry Panda is a Chinese food delivery platform targeting overseas Chinese and international students. Pictured: a screenshot from a Hungry Panda video advertisement. Image source: Hungry Panda’s official website.
To be honest, I hope they come and eat in. It’s not just that a piping-hot product is a better experience. More importantly, for the same order — delivery versus dine-in — the amount that actually ends up in our pockets as merchants is very different. UK food delivery platforms charge small food and beverage businesses like ours a commission rate of 35% plus VAT (value-added tax). What comes back to our account is only 58% of the order.
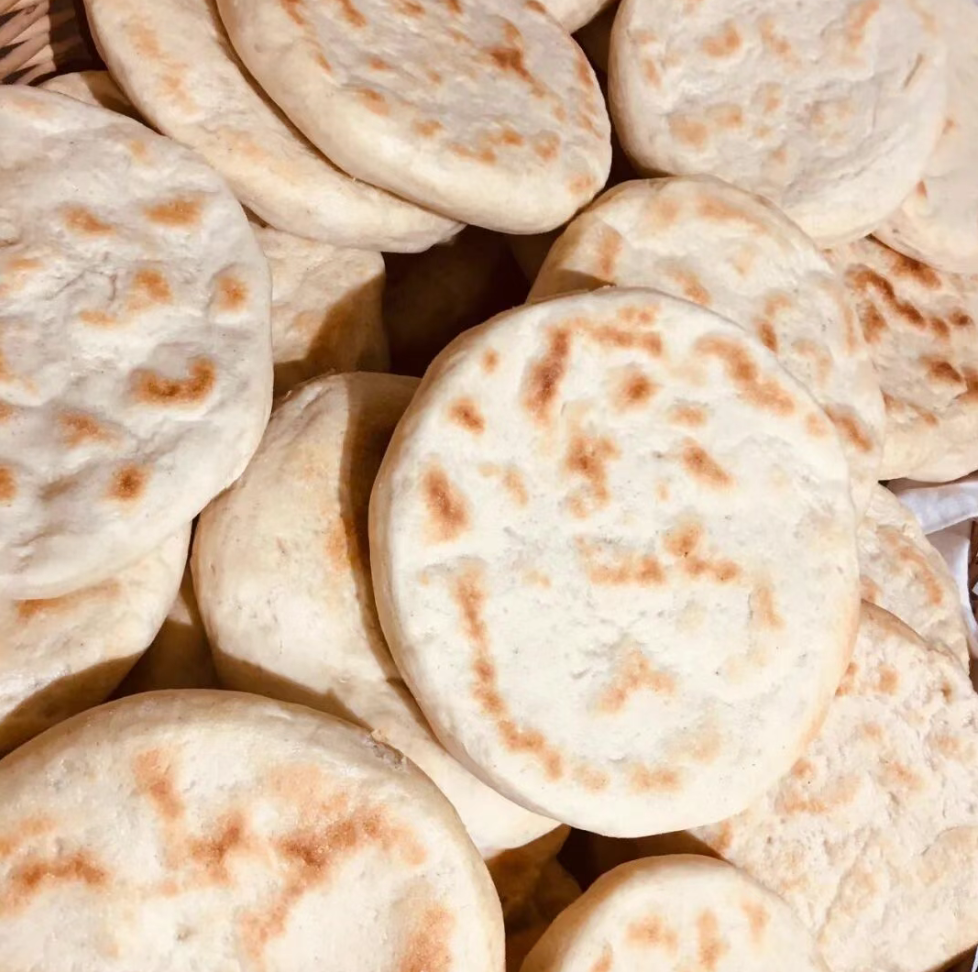
◉ Piping hot, freshly baked flatbread.
But I won’t follow what so many merchants back in China do — keeping delivery prices at par with, or even below, dine-in prices despite the platform commission already being steep. Even taking into account the need to maintain our presence on the platform and drive traffic to the restaurant, we still mark up our delivery prices by 20%, so we lose a bit less. I’ve had brief conversations with some of the fine restaurant owners in town, and their prices on delivery platforms are higher than their in-store prices too. That’s a cost customers need to bear.
This is the principle I’m talking about — whoever benefits, pays: if you want to spend less, come in; if you want the convenience, then you pay for the convenience. It’s just three or five minutes from the apartment to the shop — barely a couple of steps. If customers insist on enjoying this kind of delivery service, then they must pay the cost it rightly entails — to the riders, to the platform.
For us merchants, costs are fixed. Rent, staff, utilities and all manner of other expenses don’t go down just because you place a delivery order. So, by my logic, these extra delivery costs should fall on the customer.
On the Food Delivery Wars
Last year, when Meituan, JD.com and Taobao Flash Purchase were locked in a three-way subsidy war, I kept close watch as a food and beverage entrepreneur. I can offer a comparative perspective here, grounded in my experience of food delivery in the UK.
In these six years, I haven’t seen any turf war among the UK platforms, nor any complicated subsidy campaigns. As I mentioned earlier, UK delivery platforms charge a commission rate of 35%. Many people assume this is far higher than the rates charged by Chinese platforms. But back home, beyond the headline commission rate of 20–25%, there are all manner of subsidy and special-voucher promotions that leave merchants footing most of the cost. When you work out what actually lands in your account, the bottom line is probably not so far off from mine.
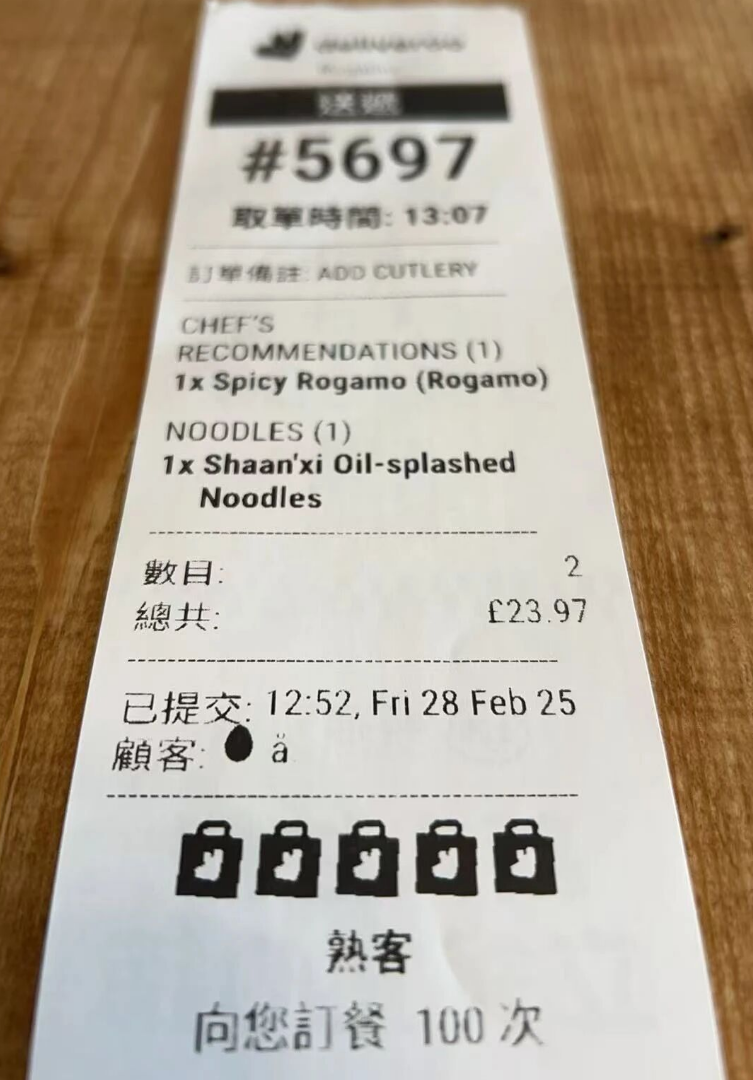
◉ A delivery order from the Rogamo shop.
So the main difference between the two comes down to this: the operational model of UK delivery platforms is simple and transparent — it is, at its core, a delivery service. I bring you your meal; you pay for the delivery. The commission comes out of the merchant’s side, the delivery fee is charged to the customer, and everything is plain to see. No convoluted tricks, no games.
This is the normal operating logic of a delivery platform, unlike the Chinese platforms, which start with massive subsidies to lock in every party, distorting the cost structures of so many merchants that they die once the platform cuts off the subsidies;
then the platforms require merchants to co-subsidise customers and attract users alongside them, demanding that merchants give back the subsidies they had previously received. Later still, the platforms stop subsidising altogether — only merchants keep subsidising. You won’t play along? Fine — customers on the platform will simply go to another merchant. Only at that point does the penny drop, but it’s already too late. Every merchant on a delivery platform has been thoroughly locked in, with no bargaining power left. Apart from the top-tier food and beverage brands — where the platforms have some room to negotiate in order to attract and retain traffic — there is nothing left to haggle over.
Finally, the platform makes you buy traffic, purchase search rankings, so that your shop might appear near the top of the delivery page. Otherwise, by the time customers finally scroll down to your shop, the moment has long since passed.
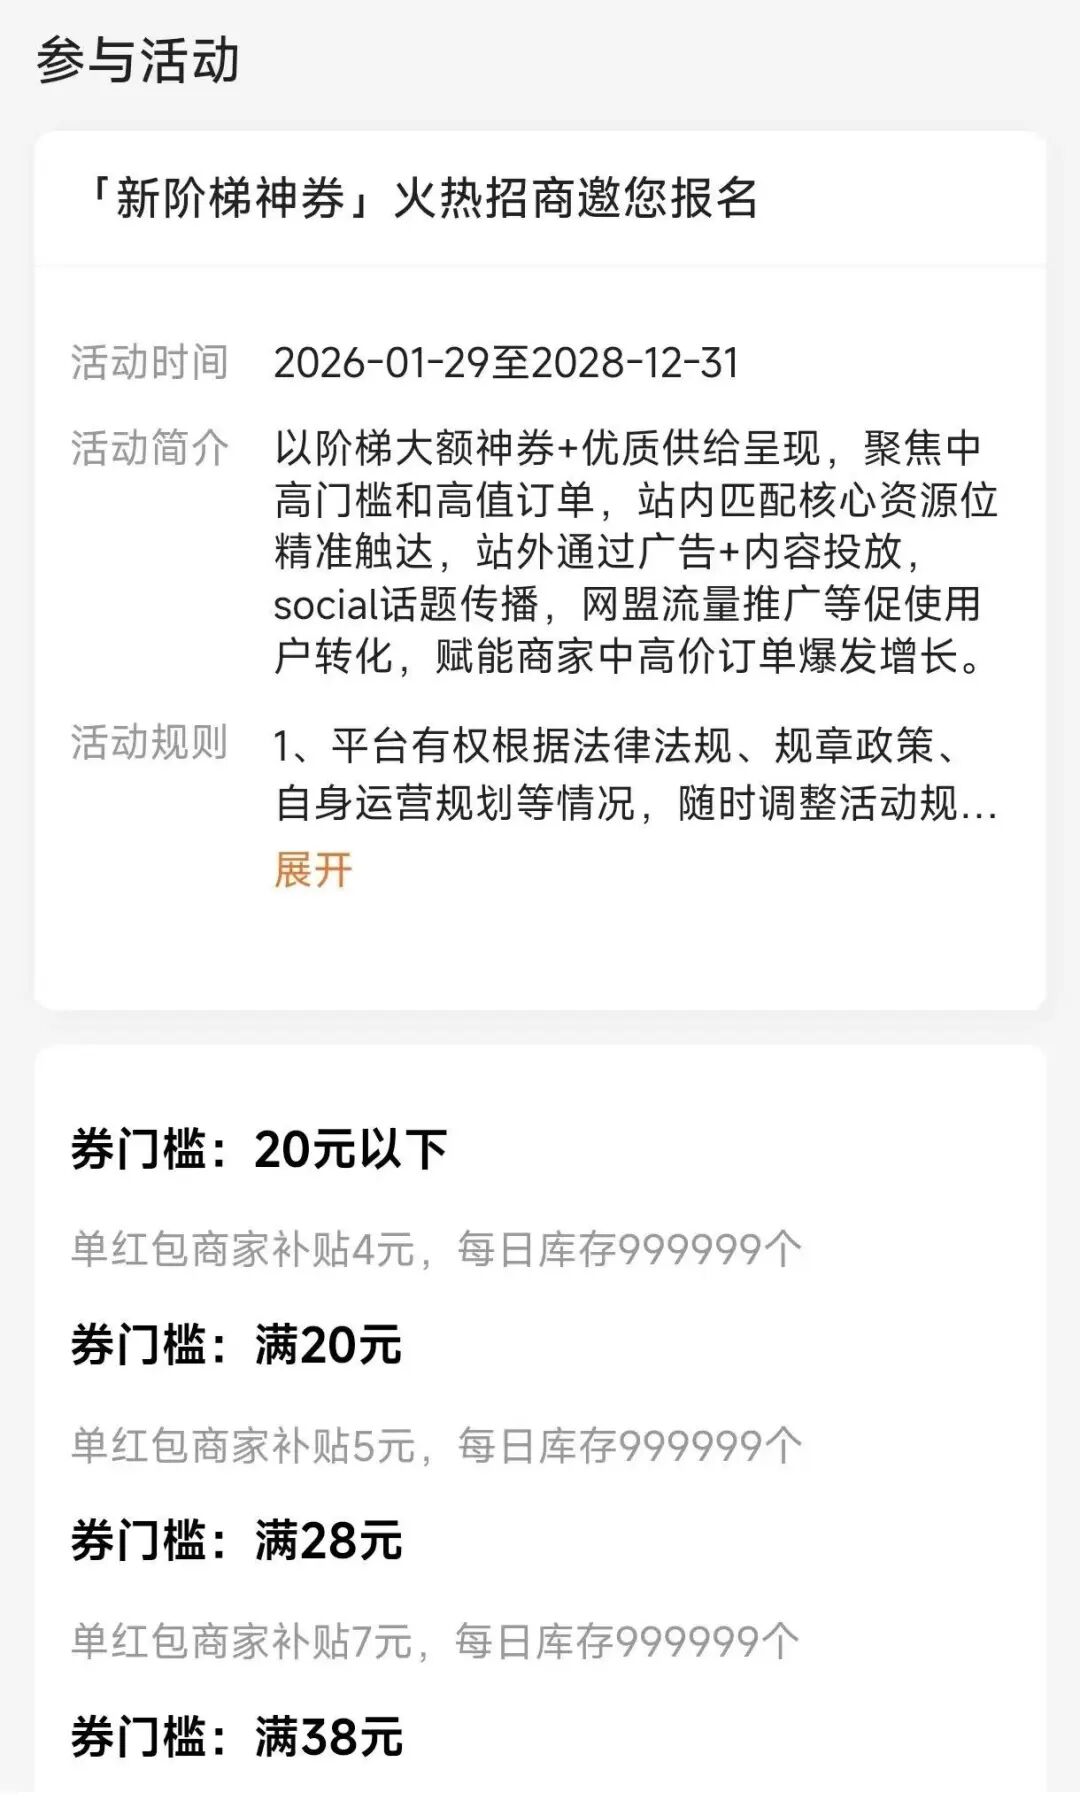
◉ Pictured: Meituan’s recently launched tiered special-voucher campaign, which refines the previous 5–6 tiers of tiered special vouchers into 9 tiers spanning 0–128 yuan, with the merchant contribution range adjusted to 5–22 yuan. A research team has pointed out that the core of this subsidy adjustment is not whether the tiers have been refined, but that the platform has further shifted subsidy costs onto merchants by introducing additional tiers. Image source: screenshot from the Meituan app
Having dealt with platforms ever since the group-buying era, I can see things very clearly. During the Hundred Groups War, I told the canvassers who came to my shop: “I already have foot traffic. Your platform is the one that wants to acquire users from my shop — you should be paying me.”
Six years ago, when Rogamo first opened, we went live on all four UK platforms. But to this day, whether for dine-in or delivery, I have not done a single bit of promotional advertising — no offers, no discounts. Every time Hungry Panda runs a joint promotion with merchants, they reach out to us, inviting our shop to take part. I’ve never once agreed. I tell them: “If the platform is subsidising the customer, go ahead by all means. If you want the merchant to subsidise, I won’t take part.”
Users attracted by offers, subsidies and discounts are essentially ineffective users — they place an order to grab a bargain, not because your food tastes good. Drawing on more than a decade of experience in the food and beverage industry, I can tell you that these customers rarely become regulars after the promotion ends, and some even leave negative reviews. It just isn’t worth it. The customers who truly love your shop do so because the food you cook is good. Our customers have built up through word of mouth over the years, and even now, from time to time, someone will take a two-hour train from London just to eat at our shop.
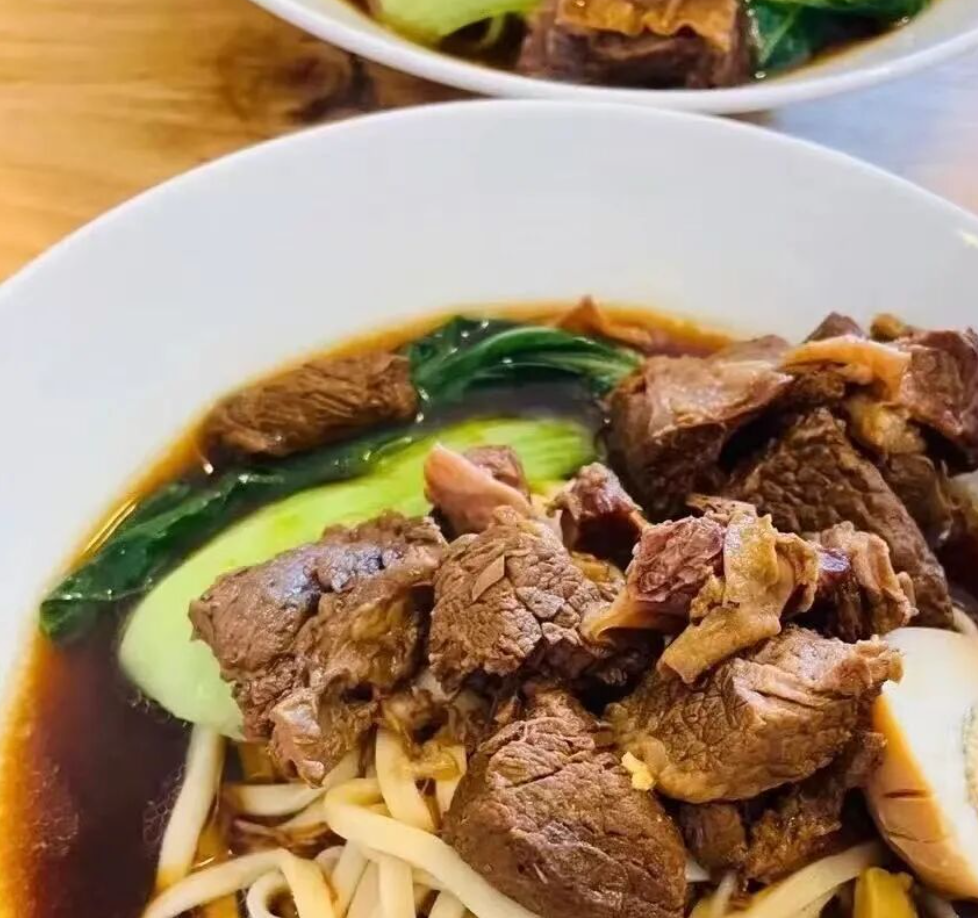
◉ There’s a young man — we’re open six days a week, and he comes at least four or five times. Every time, all he orders is a bowl of braised beef noodle soup with a side of sizzling chilli oil. One day he said to me in Chinese: “This is my favourite, No. 1.”
For certain special dishes, such as pork intestine noodle soup or the occasional batch of Old Beijing luzhu — a traditional stew of pork offal, tofu and flatbread — I don’t put them online. If you want them, come to the shop. Mainly because if you add another 20% on top of those dishes, the online price becomes even steeper. When students come in to dine in and see the same dishes priced lower than on the delivery platforms, they make a point of eating in — the experience is better anyway. In my philosophy of running a food and beverage business, foot traffic should come from the food itself, not from platforms and subsidies.
Of course, this logic holds only on the premise that UK delivery platforms have not developed to the point of being able to fully control both user and merchant resources. This may well be connected to factors such as the UK not having China’s vast pool of cheap labour, a relatively concentrated food and beverage industry, and many chain restaurants running their own delivery services. But in any case, within this context we can recognise that the development of the food delivery industry need not be built upon holding merchants’ livelihoods and consumers’ dietary health hostage to platforms’ traffic and profit logic.
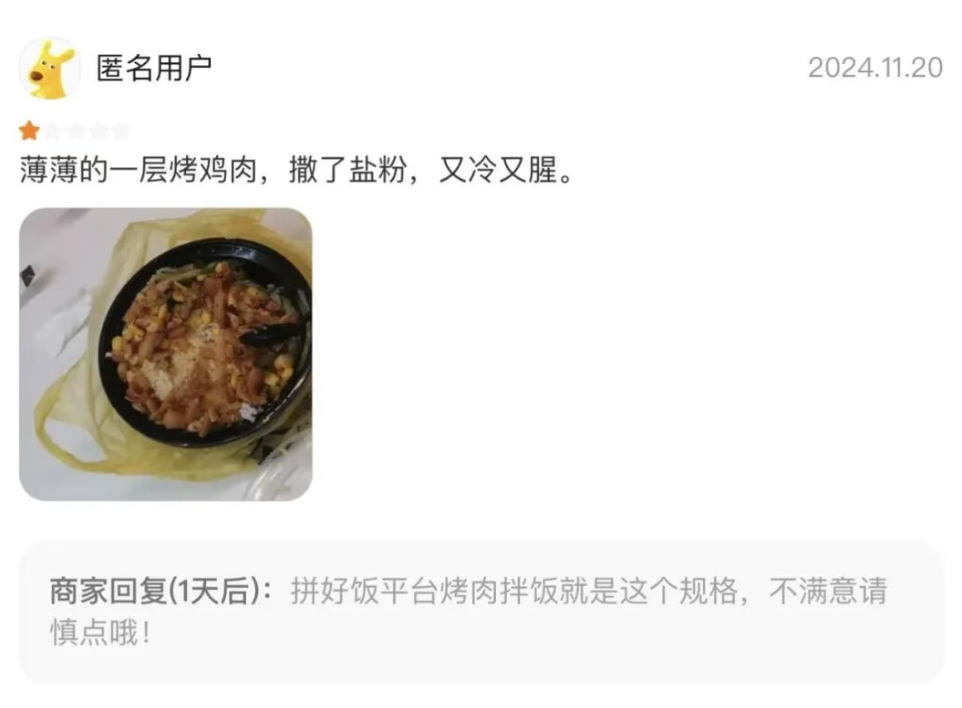
◉ Meituan’s Pinhaofan service uses traffic as a weapon to drive product prices down, forcing merchants to cut costs on ingredients. Pictured: user feedback and merchant responses from Pinhaofan. Foodthink previously described and analysed this budget-delivery model in “Pinhaofan: Who’s Actually Getting a Good Meal?”. Image source: screenshot from the Meituan app
One could say that the domestic food and beverage delivery industry was born over the past decade-plus, coaxed into existence by abnormal subsidy wars. More than a decade of this has made us forget what a normal food delivery model should look like. But as an industry that touches on public livelihood and health, the time has truly come for us to think about how the food delivery industry should develop.
Taking It Slowly Is Quite Fine
In the UK, it is a long-standing tradition for customers to order online or in person and then collect their food themselves. Customers phone the shop to place an order; once it’s ready, they come in to pick it up and pay. The shop’s only job is to cook the food and pack it up neatly. Even today, with delivery platforms having reached every corner of the British countryside, plenty of takeaway shops still operate on this phone-order model.
Just Eat still offers a great deal of this kind of service, connecting a large number of such shops. Customers can order online, but they still collect from the restaurant in person. To this day, I believe this is a sound business model for food and beverage, because a shop’s service radius is only a few kilometres at most. For merchants, the key is to put their heart into the cooking — everything else is the customer’s business.
Think back to the five to ten years before delivery platforms emerged, and you’ll notice that daily meals and the pace of life in China were nowhere near as rushed as they are now. Back then, I worked at a newspaper. When we were too busy to go downstairs for a meal, we would order food in — but we didn’t even call it “delivery” then; it was simply “takeaway”. The model was refreshingly straightforward: restaurants nearby would leave their menus and flyers at the newspaper office, we would phone in our orders, the restaurants would note them down, and once the food was ready, we could either collect it from the shop or they would deliver it to us. The quality of the takeaway was identical to dining in.
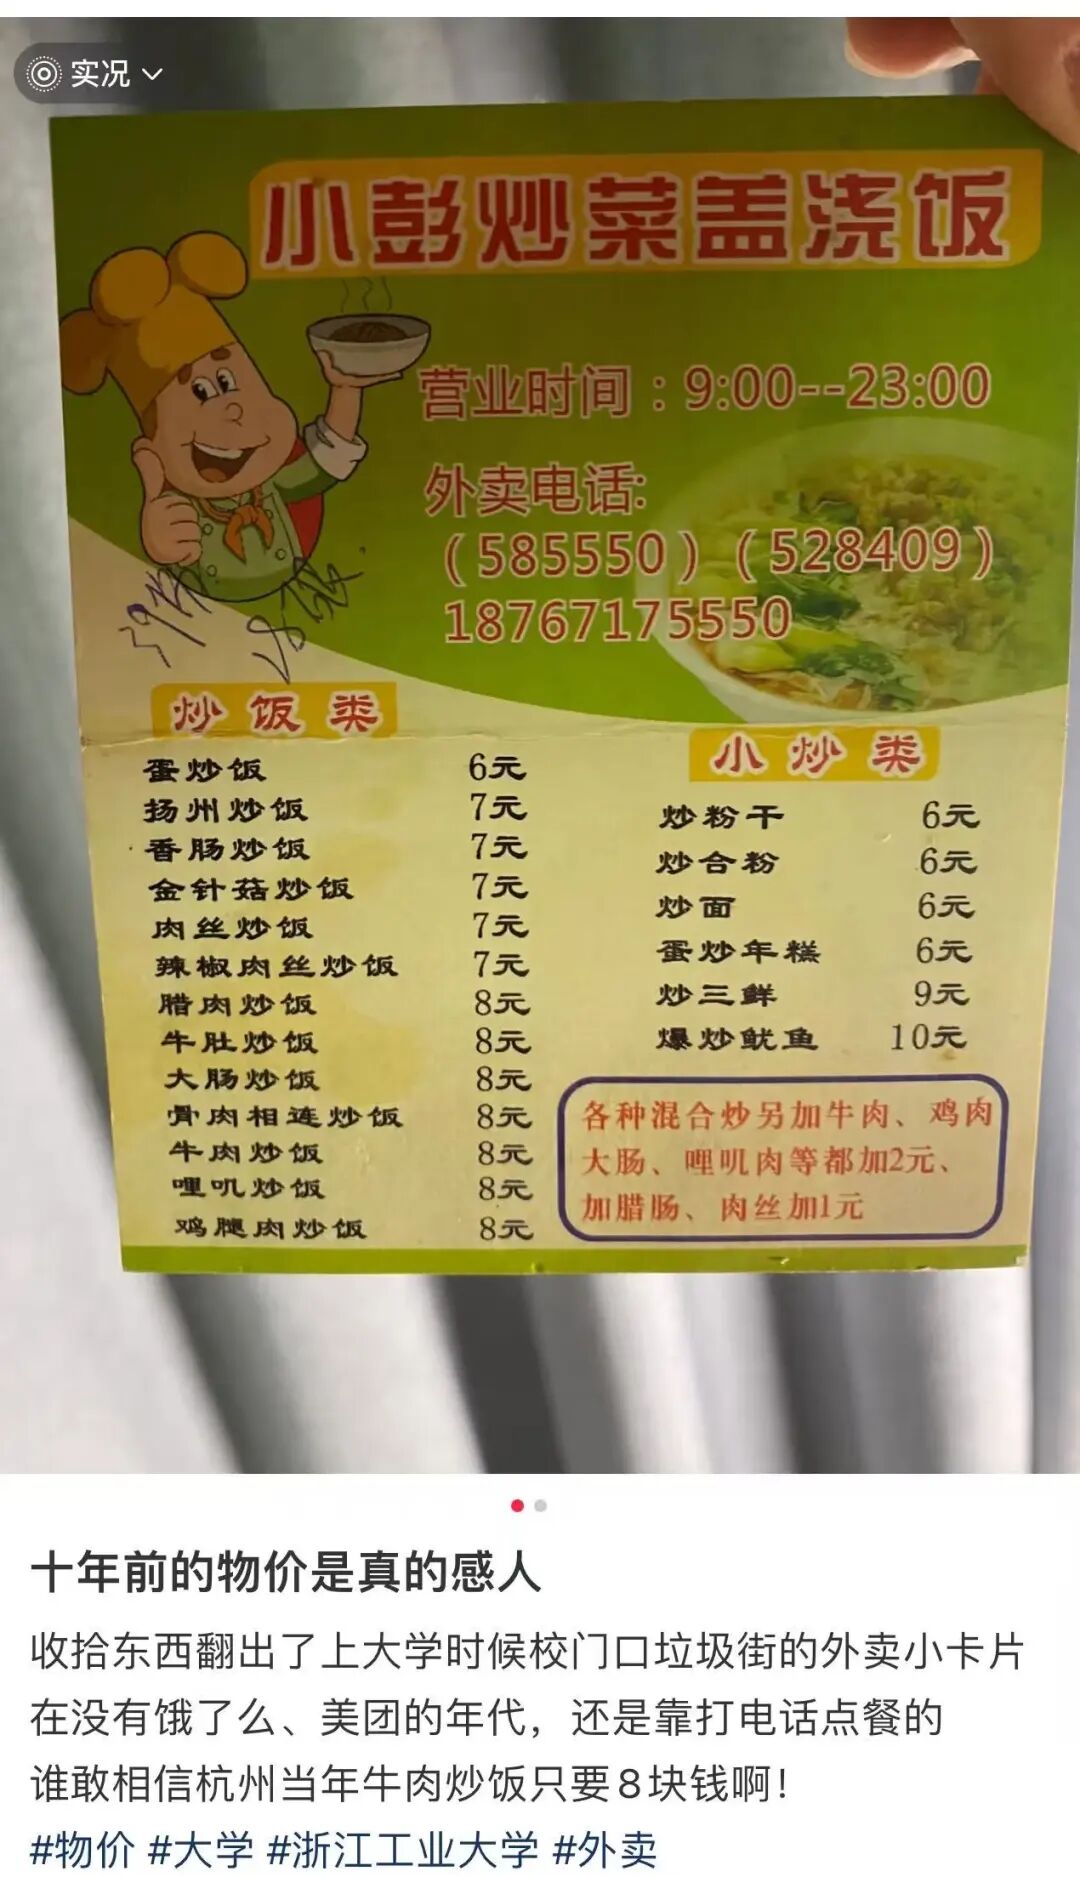
◉ Netizens have shared old flyers on social media advertising a merchant’s own delivery service. Image source: Xiaohongshu @叶不羞的修
Now, the pace of eating and living has been driven ever faster by delivery platforms. Under the platforms’ irrational competition, delivery windows that once stood at an hour have been gradually squeezed down to forty minutes, or even half an hour. The price? Delivery riders’ safety and ever more frequent road accidents.
When it comes to riders, in my five or six years of running a shop in this small town, over a hundred delivery riders have passed through our door, and I know most of them quite well. I can’t help wondering — are UK delivery riders also strictly constrained by algorithms in terms of delivery times? Do they face fines for mistakes? All I can say is that the riders I see work at a quite unhurried pace, and they never seem rushed when making a delivery.
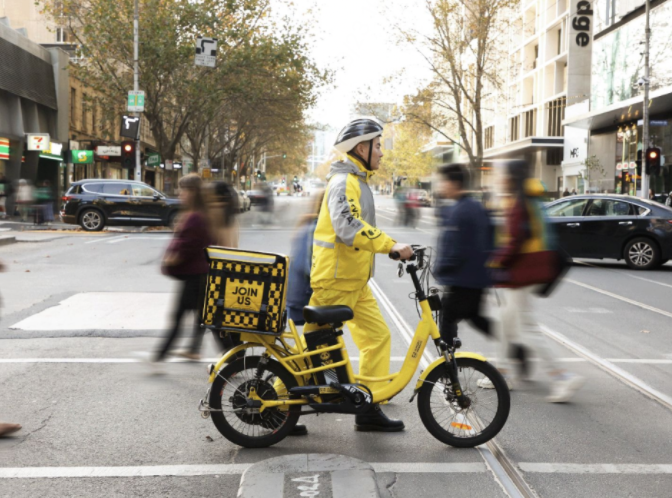
◉ A Hungry Panda delivery rider delivering an order. Image source: Hungry Panda’s official website
People in this small town take their time with meals too, and they’ve gradually grown to love the flavour of roujiamo. I, too, take my time in the kitchen, practising my philosophy of food and beverage at a gentle pace here. And so, taking it slowly — it’s quite fine.
– This is Foodthink’s 806th original article –
Foodthink
Author
Ru
A food and beverage entrepreneur with over a decade of experience, currently writing a book called Selling Roujiamo in Britain
Editor: Yuyang
Layout: Minglin
▼
Click the image to read related articles