Expert Lawyer Details the Differences Between JD and Meituan’s Social Insurance Plans
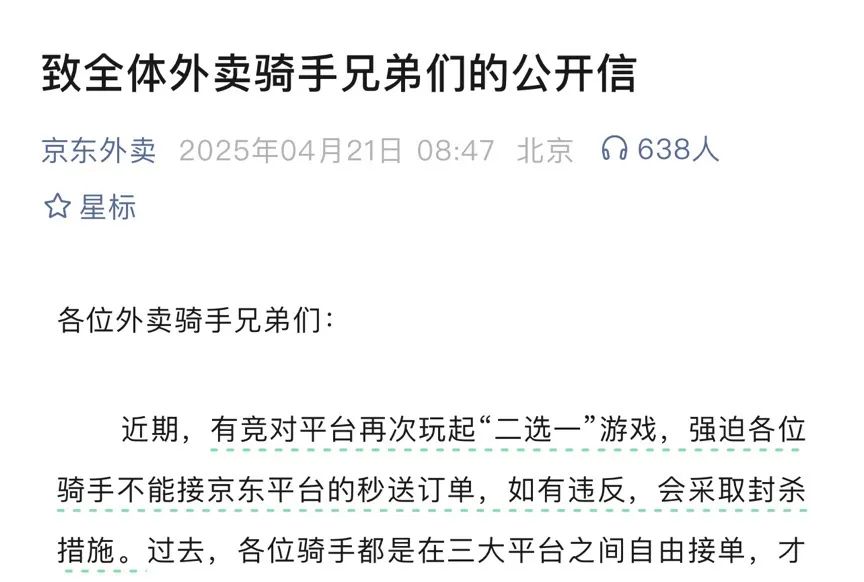
JD and Meituan are locked in fierce competition in the food delivery market, and the most conspicuous battleground has been the fight over riders’ social insurance. On 19 February 2025, JD was the first to announce full “Five Insurances and One Fund” contributions for its full-time riders, and Meituan and Ele.me subsequently pledged to pay social insurance contributions for their riders as well. On 21 April, JD published a post taking veiled aim at Meituan over issues such as “not paying social insurance contributions”, “imposing forced exclusivity on riders”, ‘ghost kitchens’ and “algorithmic exploitation”. Meituan responded the very same day: ‘Rather than spreading rumours for clicks, better to make good on your promises.’ On 13 May, the State Administration for Market Regulation and four other government departments jointly summoned JD, Meituan, Ele.me and other platform companies for regulatory discussions over prominent problems in food delivery industry competition.
I. JD vs Meituan: Social Insurance Plans Worlds Apart
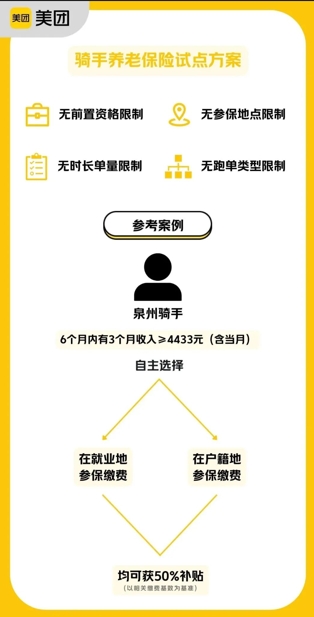
So where exactly do the two plans differ?
The first point of divergence is whether an employment relationship is recognised. JD’s plan acknowledges that its full-time riders have an employment relationship with the platform; Meituan’s plan sidesteps the question of employment status: by supporting full-time riders in enrolling in flexible-employment insurance, it effectively denies that an employment relationship exists between full-time riders and the platform.
The significance of an employment relationship should not be underestimated – it means riders stand to “receive” considerably more: severance pay upon termination of the employment relationship, paid annual leave, double penalty for wage arrears, continued normal pay during employer-ordered work stoppages, increased income from housing provident fund withdrawals, unemployment benefits, and so on.
Secondly, the two plans cover different numbers of insurance types, resulting in different levels of protection. JD’s “Five Insurances and One Fund” comprises pension, medical (including maternity), unemployment, work-injury insurance and the housing provident fund, whereas the flexible-employment insurance Meituan subsidises covers only the basics – pension and medical.
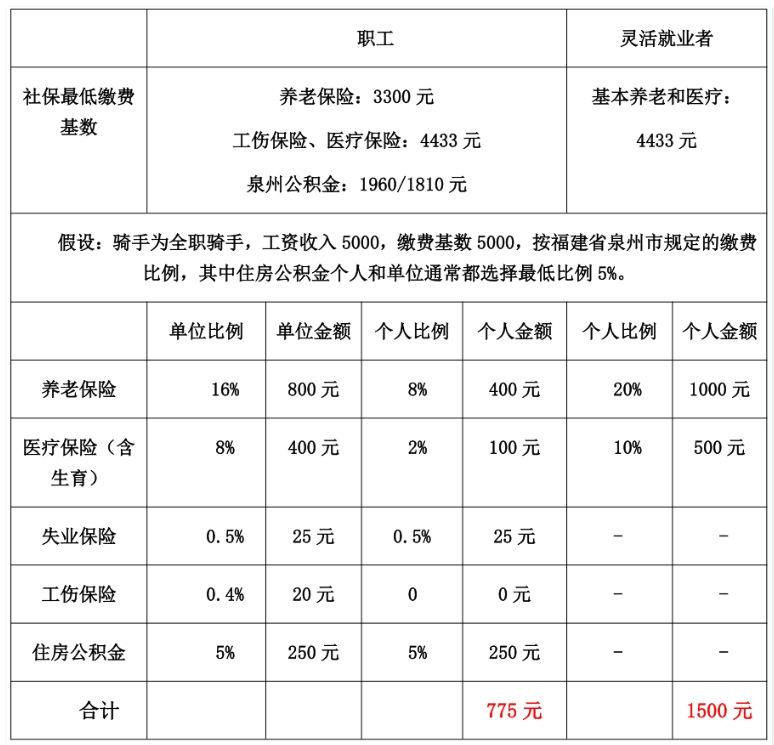
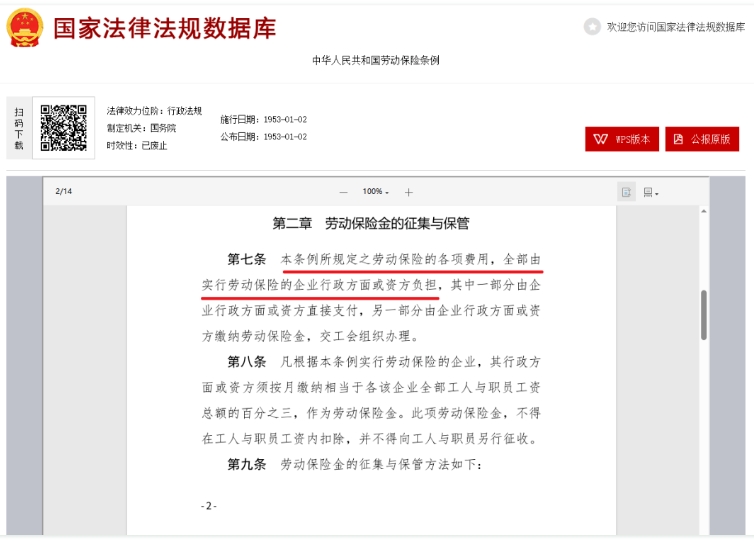
The third difference is the cost borne by riders personally. In practice, the social insurance contributions made under the flexible-employment scheme are no less expensive than those under the enterprise-employee scheme. Take Quanzhou, Fujian, where Meituan runs its pilot, as an example. In April 2025, using a contribution base of 5,000 yuan, the personal costs for a rider earning 5,000 yuan a month under each scheme are as follows:
Finally, there is the matter of benefits.
First, it is evident that JD’s enterprise-employee social insurance plan covers more insurance types, entitling riders to work-injury insurance benefits and unemployment insurance benefits on top of what Meituan’s plan offers.
Secondly, pension benefits may differ by as much as thirty-fold. Under JD’s plan, riders bear a lighter personal cost, making them far more likely to sustain contributions over the long term and ultimately draw an urban employee pension. Under Meituan’s plan, the heavy personal burden makes it difficult for riders to sustain contributions for fifteen years; many simply stop contributing or let their contributions lapse, eventually falling back on urban-rural residents’ insurance.
According to academic research, the average monthly pension received by urban enterprise employees in China is 30.23 times that received by urban-rural residents. For illustration, in 2017, the average monthly pension for urban-rural residents was around 120 yuan, meaning urban employees would receive approximately 3,627.6 yuan per month.
So, overall, compared with Meituan’s plan, JD’s plan recognises the employment relationship, entails lower contribution costs, covers more insurance types, and offers additional income through housing provident fund withdrawals – making it far better value for money.
On balance, for full-time riders, JD’s and Meituan’s plans could truly be said to be worlds apart!
II. How Do Riders Feel About Paying Social Insurance Contributions?
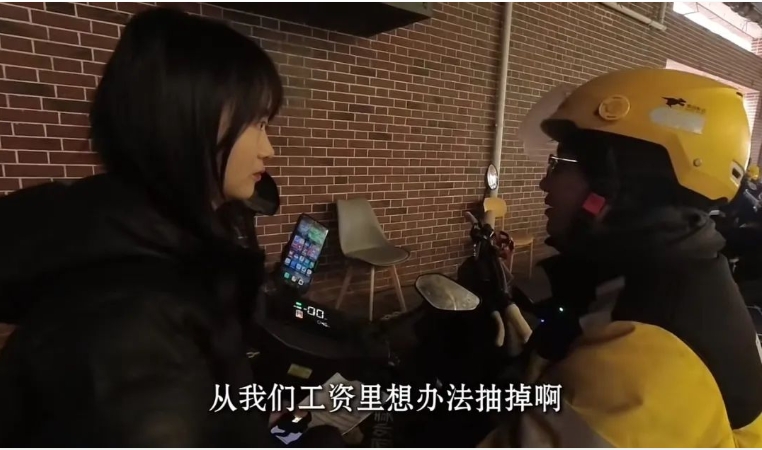
“This is a form of protection – of course I want it.” When Xiao Bao learned that JD intended to cover the full “Five Insurances and One Fund” contributions for riders at no cost to them, this was his reaction. At eighteen, he had been working crowdsourced delivery for Meituan for six months. He figured that if contributing to social insurance meant paying a few hundred yuan out of his own pocket each month, he would need to compare the pay on offer from Meituan and JD. “If they pay into social insurance and the wages are about the same, I’ll work for JD.” But then he added, “I might not ride for a living long-term anyway – if I contribute, will I actually be able to use it later?” He hadn’t even finished secondary school, and his understanding of the specific social insurance policies was far from complete.
Xiao Li, 35, had been delivering food in Beijing since 2018 and was now a dedicated delivery rider for Meituan. He completed a high volume of orders and earned a good income. But since 2019, the per-order rate had fallen sharply, and to maintain a high income he now worked virtually every day, logging at least twelve hours a day. He had no objection to contributing to social insurance – he thought it was a good thing – but as yet, there had been no news from his station.
Old Jia, 45, was also a dedicated delivery rider for Meituan in his first full year on the job. He had seen a great deal of life and spoke with hard-won perspective. He had once worked his way up from the shop floor to workshop supervisor at a state-owned factory, only to be laid off. After that he had worked as a courier for SF Express but was dismissed for a mistake. “When we get old and can’t work any more, we can only rely on our pension. The social insurance JD contributes to may not match the pension benefits you get in the public sector, but without any contributions at all, there’s no safety net whatsoever.” He understood that social insurance was a form of protection for himself, so whether a job included contributions was something he had to consider when looking for work. So why had he taken the job at Meituan? “I was just conned!” He laughed ruefully. “The online job ad said riders would get social insurance contributions, but only after three months on the job. Well, it’s been a year and they still haven’t paid in.” For now, though, the income from riding was not too bad. Jia and his wife were both working in Beijing, and they were scraping by. There was nothing for it but to keep going.
“Those factory workers and people with job security – they get sick leave and proper rest breaks. For us, that’s an unthinkable luxury. It’s not just about surviving but about actually enjoying life – that’s a luxury I can’t dream of.” Old Li, 59, an Ele.me rider, sighed. “JD’s ‘Five Insurances and One Fund’ is an even greater luxury. At my age, nearly sixty, I couldn’t join a team like that anyway. It would be wonderful if everyone had it – I think it would be such extraordinary treatment for us, truly wonderful.”
We must not forget the very essence of social security – that it exists to relieve individuals of the sole burden of bearing risk. The modern social insurance system was pioneered by workers in the early days of industrialisation who, afflicted by workplace accidents, unemployment, illness and old age, were unable to earn a living, and it was first enshrined in law in Germany, where the workers’ movement was most developed. On 10 June 1907, US President Roosevelt said in a speech that work which causes accidents is “done for the employer, and therefore ultimately for the public – to make the worker and his wife and children bear the whole loss is an intolerable injustice”. This idea set the course for a transformation in American law, replacing nineteenth-century common law with a government-mandated insurance system.
China’s Constitution provides that “citizens of the People’s Republic of China have the right to material assistance from the state and society when they are old, ill, or have lost the capacity to work.” In other words, workers who have contributed a lifetime – or even their health – to building society should be provided with the basic material conditions for survival and recovery when they can no longer work and earn a living.
III. Would Paying Social Insurance Contributions for Riders Make Meituan Run at a Loss?
The grievance Meituan wishes to air is this: I’m already making a loss without paying social insurance contributions – wouldn’t contributing only bankrupt me? But is that really the case?
A closer look at Meituan’s financial reports reveals that the delivery service revenue the company cites is not equivalent to the overall revenue of its food delivery business. In other words, the total revenue of the food delivery business is far more than RMB 82.19 billion.
This is because delivery service revenue is primarily composed of the delivery fees jointly paid by consumers and merchants for each order. However, on the merchant side, what is owed to Meituan goes far beyond the “fulfilment service fee” (that is, the delivery charge borne by the merchant). There is also the “commission” that merchants must pay the platform in order to operate their food delivery business.
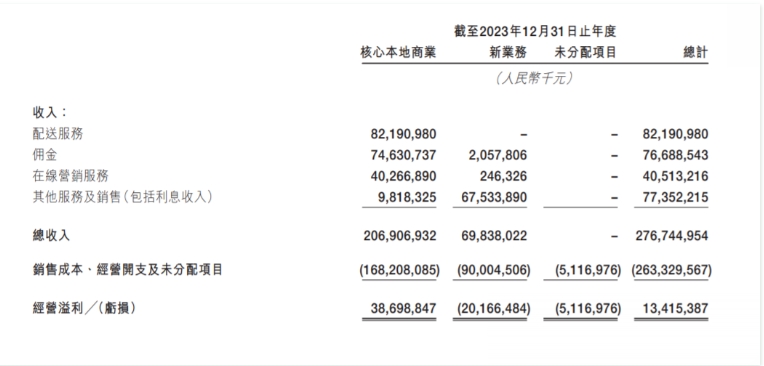
In fact, before 2021, Meituan referred to both the “fulfilment service fee” and the “commission” collectively as “platform service fees” – meaning that even Meituan itself implicitly acknowledged that both were revenue generated by the food delivery business.
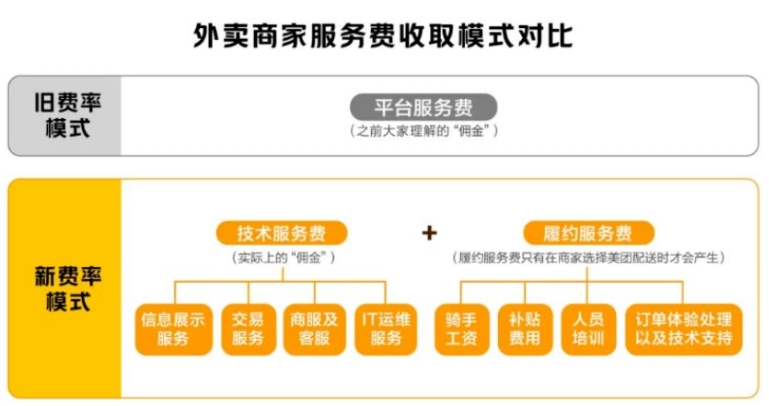
It is therefore simply untrue to say that Meituan’s food delivery business runs at a loss, and it cannot be used as a justification for not paying social insurance contributions.
Furthermore, Southern Weekend once worked through the following calculation in a report: if Meituan were to pay social insurance contributions for 10 million riders, its costs would increase by RMB 21.6 billion, while Meituan’s full-year profit for 2023 was RMB 23.25 billion. This, it was argued, still gave Meituan a “legitimate” economic reason to resist contributing to riders’ social insurance.
However, a careful reading of Meituan’s financial reports shows that a substantial portion of its overall profits was channelled into investment in new business segments – Xiaoxiang Supermarket, Meituan Shangou, Meituan Youxuan, and others – with the aim of further market expansion. In 2021, 2022 and 2023, Meituan’s new business segment posted losses of RMB 38.4 billion, RMB 28.4 billion and RMB 20.2 billion respectively. Despite these persistent losses, Meituan did not halt its expansion. By 2024, losses in the new business segment had narrowed to RMB 7.3 billion, suggesting the expansion strategy was beginning to bear fruit.
Furthermore, research and development in new technologies such as drones and autonomous delivery vehicles has been another major area of Meituan’s capital investment; in 2024, Meituan’s R&D spending reached as high as RMB 21.1 billion.
These figures alone should surely be more than enough to cover the RMB 21.6 billion social insurance cost. In reality, they serve as a mirror-image proof of a troubling truth: Meituan’s “business-technology” empire has been built at the expense of riders’ rightful social security entitlements.
IV. Will Paying Social Insurance Contributions for Riders Become the Norm?
Several business analyses have pointed out that it is precisely the continued expansion of Meituan’s and JD’s commercial empires that has brought their respective businesses into ever closer overlap in the instant retail market. It is only under this competitive landscape that the issue of social insurance contributions for riders has seen new developments.
“Zhongbaozai Xiaoyu”, a Bilibili content creator who works as an Ele.me rider, has observed that since JD’s food delivery service entered the competitive arena, riders’ conditions have noticeably improved. Incentive campaigns have become more frequent, and in bad weather riders now not only receive bonuses but also see their delivery time limits extended – something that had “never happened before”.
But we must not forget that in 2015, when Baidu Waimai, Koubei Waimai and Ele.me could still compete vigorously with Meituan, the per-order rates and subsidy packages for delivery riders across all platforms were far more generous than they are today. Yet all of that disappeared once Meituan achieved a monopoly.
Will history repeat itself? We need to observe these changes with sustained, cautious attention. At the very least, it has indeed broken the “norm” that platforms need not pay social insurance contributions for riders, and we can seize this opportunity to think about what kind of social insurance model riders – and workers more broadly – truly need.
‘Notice of the Fujian Provincial Department of Human Resources and Social Security, the Fujian Provincial Department of Finance, and the Fujian Provincial Tax Service of the State Taxation Administration on Issues Relating to Unemployment Insurance and Work-Injury Insurance Contribution Rate Policies’ (Fujian HRSS Doc [2023] No. 48)
“Notice on Adjusting Work-Injury Insurance Contribution Rate Policies” (MOHRSS [2015] No. 71); “Notice on Issues Relating to Unemployment Insurance and Work-Injury Insurance Contribution Rate Policies” (Fujian HRSS Doc [2023] No. 48); “Implementation Opinions on Provincial-Level Centralised Administration of Work-Injury Insurance in Fujian Province”. According to research, the registration authority classifies online platform delivery riders under the resident services industry, with a work-injury insurance contribution rate of 0.4%.
“Regulations on Housing Provident Fund Management in Quanzhou”
[Sweden] Edward Palmer, Wang Xinmei, and Zhan Peng, “The Public Pension of China’s Urban–Rural Integration: Building a Virtuous Circle between Employee and Resident Insurance Schemes”, Social Security Review, 15 January 2022, Vol. 6, No. 1
Yang Yansui and Qiu Yan, ’40 Years of Reform and Opening Up: From “Retirement Pension” to “Pension”‘, China Human Resources and Social Security, Issue 12, 2018.
[USA] John Fabian Witt, trans. Tian Lei, Accident of Empire: Injury and Death in the Republic of Work, China University of Political Science and Law Press, 1st edn, March 2016.
Yang Yansui and Qiu Yan, ’40 Years of Reform and Opening Up: From “Retirement Pension” to “Pension”‘, China Human Resources and Social Security, Issue 12, 2018.
(Meituan, “Meituan Subsidises Riders’ Pension Insurance – Pilot Programme Launches Today”)
‘In China, the benefit gap between government agencies and public institutions on the one hand and enterprises on the other, within the employee insurance scheme, stands at 2.27 times.’ [Sweden] Edward Palmer, Wang Xinmei, and Zhan Peng, “The Public Pension of China’s Urban–Rural Integration: Building a Virtuous Circle between Employee and Resident Insurance Schemes”, Social Security Review, 15 January 2022, Vol. 6, No. 1
Meituan Financial Reports 2021–2024, https://www.meituan.com/investor/reports
What Is Meituan’s True Commission Rate on Food Delivery? https://www.meituan.com/news/NN241225051008799
How Much Do Meituan and JD Actually Overlap? | Zhaobo Weekly https://mp.weixin.qq.com/s/tDlqxcDnBz9DVbnjemztdw
Editor: Yuyang