Behind RMB 5.2 Trillion in Coverage: The Truth About Agricultural Insurance Claims Settlement
Foodthink says
Recently, heavy rain and hailstorms have been frequent across the country, again striking many crops at critical growth stages. As a result, farmers face enormous losses.
In public discourse, whenever the risks that climate change poses to agricultural production are discussed, experts, the public and even policy makers invariably reach for “agricultural insurance” as a lifeline. Yet the current state of agricultural insurance implementation in our country, farmers’ attitudes towards it, and whether insurance is automatically the same as protection—these specific questions have rarely been examined in depth.
In the latest episode of the podcast “Food Talk”, we interviewed Yi Fujin, director of the Zhejiang University Research Center for Agricultural Risk Management and Safe Development. He explained in detail how farmers receive agricultural insurance compensation, and why some farmers do not receive compensation and do not trust agricultural insurance. More importantly, agricultural insurance is also facing growing claims-payment pressure; as the climate continues to change, how should this policy-based insurance develop?
The topic of agricultural insurance is highly complex and may be difficult to fully understand or digest through a podcast alone. Foodthink has therefore prepared a condensed text version of this episode for readers to read and search through.
How Much Has Agricultural Insurance Paid Farmers?
Q
According to data from the Ministry of Finance, China’s agricultural insurance premium scale has exceeded RMB 155 billion in 2025, providing more than RMB 5.2 trillion in risk protection for 125 million farming households. How should these figures be understood?
Yi Fujin: RMB 155 billion represents premium income, that is, premiums paid by farmers plus premium subsidies provided by governments at all levels, amounting to RMB 155 billion. The RMB 5.2 trillion risk protection level assumes that all insured items are damaged; if claims are capped at the actual sum insured, the amount would be RMB 5.2 trillion, accounting for 60% of national agricultural GDP, which is already very high. But RMB 5.2 trillion is not readily available cash; it relies on the accumulation of premiums over many years before it can be paid out in one go, and it is a rather notional figure. In fact, it is unlikely that such a large payout would occur all at once. What should really be looked at is RMB 155 billion; the scale of agricultural insurance premiums has now become the largest in the world. Of the RMB 155 billion, around 80% comes from government, and the remaining roughly 20% from premiums paid by farmers.
Q
The farmers we met actually gave rather different accounts of agricultural insurance compensation. Some successfully received relatively satisfactory compensation, and some even treated agricultural insurance as a form of wealth management, while others were unable to receive compensation. What possible reasons might lie behind this?
Yi Fujin: China’s agricultural production structure has a very distinctive feature: it is a “large country, small farms” situation—among the principal actors in China’s agricultural production, about 97% are smallholder farmers. This basic reality means that agricultural insurance cannot achieve 100% precision in its implementation. Moreover, given the complexity of agriculture itself, agricultural insurance also finds it difficult to provide individualised services household by household and farm by farm in the way that motor insurance or property insurance can.
Last year, during our fieldwork in Henan, we saw a very typical township with more than 20,000 mu of cultivated land and over 5,000 farming households. Insurance company staff at the grassroots level were already very stretched. Generally, one grassroots staff member at an insurance company is responsible for 2–3 such townships, and in some places even more. In other words, one person may have to cover 40,000–50,000 mu of land and over 10,000 farming households. The difficulty is further compounded by the fact that agricultural production is extremely time-sensitive, which is also why the state places very high demands on the timeliness of agricultural insurance. The basic requirement is that the entire process—from inspection and loss assessment to the payment of claim funds to individual farming households—be completed within 14 days.
But the problem is that inspection, loss assessment, confirmation and disbursement across tens of thousands of mu must be completed within just over ten days, creating enormous pressure. As can be imagined, in practice, faced with a large number of smallholder farmers, it is almost impossible for insurance companies to conduct loss assessment household by household and plot by plot. This is the biggest obstacle to implementing agricultural insurance under the “large country, small farms” national conditions.
Therefore, in some regions, an alternative model is now adopted, with a “collective insurance policy” signed at the level of the village collective. Once smallholder farmers in the village suffer disaster losses, within 14 days the insurance company randomly samples 3–5 plots within the village and uses these to make an overall assessment of the area affected and the severity of the damage across the village. It then confirms the total claims settlement amount for the village based on the average level of loss. Once the amount has been confirmed, village committee cadres (who are in fact auxiliary insurance staff employed by the insurance company) allocate it according to the actual situation in each household, completing claims settlement for each smallholder farmer.
This leads to two possibilities.
The first type is that although the current model is nominally called “yield insurance” or “full-cost insurance”, in fact its operating principle is area-yield insurance, with insurance based on the average yield of the whole village. For example, a farmer’s plot may be on tidal flats and washed away after a flood, but the village as a whole may be unaffected. Under the random sampling principle, that plot may not be selected, or it may have no substantial impact on the village’s overall yield.
The second type is that, after agricultural land reform, many farming households’ cultivated land is not one continuous plot. A household’s 10 mu of cultivated land may be divided into four or five plots, and the land is even more fragmented in mountainous areas. Of the 10 mu, perhaps only one plot is affected, and, under the insurance contract terms, it may not be determined to be disaster-affected; this means the most basic payout cannot be triggered. However, farming households do not accept this. They believe that as long as the plot is affected, they should receive a payout, regardless of the amount of the loss. Because farmers have misconceptions about the basic principles of agricultural insurance, and because publicity and explanation are insufficient, farming households also have considerable reservations about agricultural insurance.
Therefore, whether due to the mechanism design or the inherent characteristics of agricultural insurance itself, so-called “erroneous and missed claims payments” are bound to occur.
For large-scale farming households, the threshold is generally at least 50 mu. In some places, such as the northeast, it may be 100 mu or 300 mu. Essentially, every province requires insurance companies to issue separate policies and sign separate contracts for such large-scale farming households. After a disaster, insurance company staff must go specifically to large-scale farming households’ homes to conduct loss assessment. By comparison, agricultural insurance is much more accurate for these farming households.
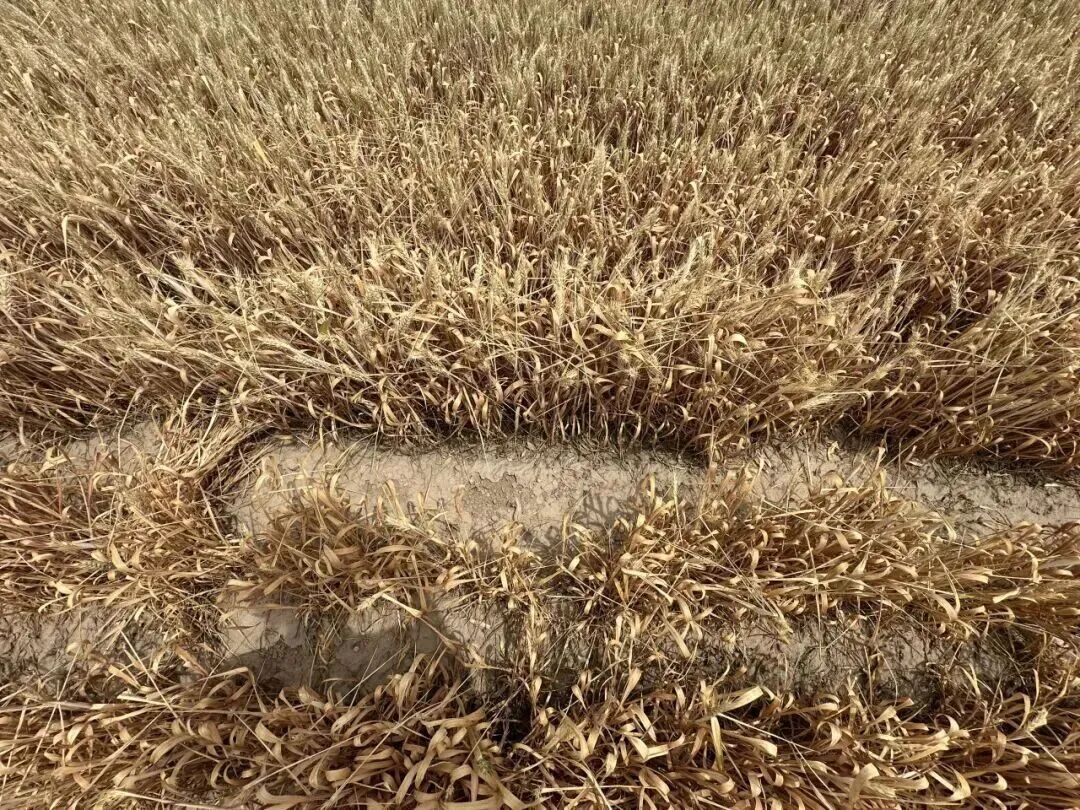
◉ In 2025, Shaanxi suffered a severe drought; wheat on the river flats south of the Wei River had yellowed and withered, and its flag leaves had all dried out; the soil at the base of the wheat was scorching hot to touch during the day. Image source: Kong Lingyu
Q
According to the principles of agricultural insurance, roughly how much agricultural insurance compensation can farmers receive, and how is it calculated?
Yi Fujin: Another reason farmers feel that payouts fall far short of their expectations is that the payouts under agricultural insurance (full-cost insurance, or materialised cost insurance) in fact cover only factor inputs.
The total cost of agricultural production is not like industrial production, in which all factor inputs are put in at once; rather, it is invested gradually. For example, at the seedling stage only about 50% of the cost may have been invested; by the jointing stage, cumulative investment is about 70%; by the flowering stage, cumulative investment is about 90%; and it is not until maturity and harvest that the full cost has been completely invested. So the payout also depends on the stage of production at which the farmer suffers the disaster.
Take a straightforward example. Suppose the disaster occurs during the wheat seedling stage, such as when a late spring frost after the Chinese New Year kills the wheat during the seedling stage. In this case, insurance companies usually do not pay out to the maximum limit of the coverage level; instead, they assess the claim based on the inputs already incurred during the seedling stage. On a total-cost basis, the seedling stage may account for only 50%. Therefore, even if the insurance contract states a coverage level of RMB 1,000 per mu, if the wheat is killed by frost at the seedling stage, the payout may be at most 50%, that is, RMB 500 per mu, because subsequent costs for the jointing stage, flowering stage and so on have not yet been incurred. If the disaster occurs at the harvest stage, for example, if lodging or sustained heavy rainfall causes total crop failure, the payout may then be at 100%. Agricultural insurance contains many technical details, but they are not set out clearly enough in the policy terms. However, in actual claims settlement, it is in fact carried out in the way described above.
Q
So why do some farming households see agricultural insurance as a form of wealth management?
Yi Fujin: In the industry, this practice is called “premium refund”. In years when farmers have not suffered disaster losses, to stabilise their willingness to take out insurance in the following year, insurance companies will provide a premium refund to farmers; once a disaster occurs, claims settlement is still carried out according to the normal process.
How should the issue of premium refunds be understood, and what are the reasons behind it? This is because the state’s payouts to the vast numbers of smallholder farmers are based on sampling-based loss assessment and are not inherently accurate, and because premiums are set at too high a level. It can even be said that such insurance is a “defective product”. To maintain farmers’ willingness to take out insurance, insurance companies have to use agricultural insurance that is not worth its price to give farmers an answer. So in practice, when no disaster occurs, insurance companies refund part of the premium to farming households.
But for agricultural insurance, this is certainly not a good thing, because what agricultural insurance ultimately hopes for is to be able to accumulate a surplus in the insurance fund when there are no disaster losses and then pay it out when a disaster actually occurs. In current practice, however, money that should have been surplus funds is being paid out. When a major disaster really comes, there will be no money left to pay claims, creating the so-called “small disaster, big payout; big disaster, small payout” problem. So the state’s 2024 No. 1 document put forward the “dual precision”—precise insurance enrolment and precise claims settlement. This issue has now become the most important real-world challenge in our agricultural insurance today.
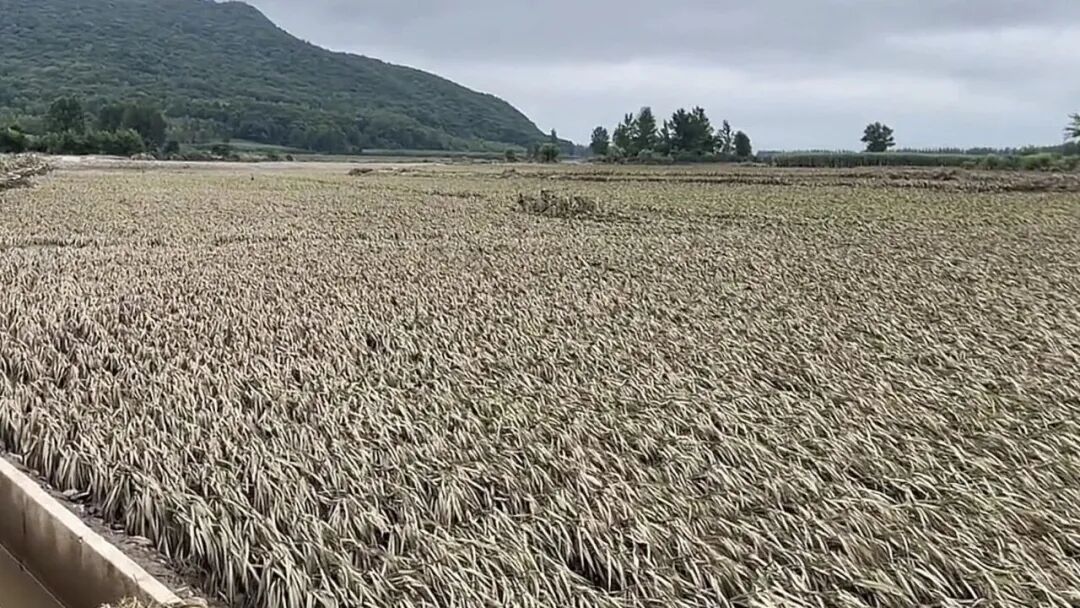
◉ Widespread lodging in a flood-soaked rice paddy, with muddy water left on the rice ears and stalks. Image source: Yvonne
Facing Widespread Disaster Losses
Can Insurance Companies Afford to Pay Claims?
Q
So if a widespread disaster were to occur, like the situation North China encountered last year, could the local insurance companies afford to pay out? For example, if a particular area suffers disaster losses, is it the local branch that pays out, or would the provincial company or the national headquarters also come in to pay this sum?
Yi Fujin: Insurance companies themselves vary considerably. For example, the largest insurance company in Henan is Zhongyuan Agricultural Insurance, which has its own branches at the grassroots level, or what are called county sub-branches. In minor disasters, as long as the amount to be paid out is not especially large, the claim can be settled through the accounts of a county-level or prefecture-level central sub-branch. However, for very large disasters, especially widespread disaster losses like those of last year, a county-level company, or a prefecture-level central sub-branch, or even a provincial-level company, simply cannot afford to pay.
This is because only RMB 40 in premium is collected per mu, while that RMB 40 has to cover a payout of RMB 200 when a farming household suffers disaster losses in that year. In other words, the premium collected is insufficient to support the RMB 200 payout amount. In this situation, the risk reserve accumulated in the past (that is, risk surplus) must be relied on to support payouts during major disasters.
As a general rule, in normal years, insurance companies set aside a “catastrophe reserve” from premiums. They also purchase agricultural reinsurance from reinsurance companies. Once a payout arises that a local company cannot cover, payment can be made from the catastrophe risk reserve, or the risk can be shared through reinsurance companies. But a major challenge now is that China has yet to put in place a very well-established catastrophe risk response system.
Ideally, at a company such as Renbao, if a local branch is in an excess-of-loss position, the headquarters can, in theory, mobilise resources across regions to coordinate. But for local agricultural insurance companies such as Zhongyuan Agricultural Insurance in Henan or Guoyuan Agricultural Insurance in Anhui, the position is much more passive. If a major disaster occurs in the area, the pressure on claims settlement can become very high, and it is difficult to spread the risk nationwide. This would lead to a situation similar to a bank run, where the company cannot pay out this much at once and may face enormous financial pressure.
In the United States, Canada, Japan and even India, emergency funds are usually established by the central government, because the fiscal budget itself already contains such emergency reserves that can be used, and public bonds can also be issued to mitigate the impact of catastrophe risk. But in China, the development of such mechanisms is still relatively weak. In 2020, China established the China Agricultural Reinsurance Company at the national level. At present, this is still done by way of 20% reinsurance—for example, if one insurance company collects RMB 1 billion in premiums in one province, it must pass on 20% of that, that is RMB 200 million in premiums and the corresponding risk, to a reinsurance company—the China Agricultural Reinsurance Company and local insurance companies have thereby formed a risk-sharing mechanism.
But this cannot fundamentally solve the problem. Because excess-of-loss risk is widespread—system-wide catastrophe risk in Henan, Anhui, Shanxi and Shandong—the reinsurance mechanism is certainly insufficient. In this situation, the operations of any commercial insurance company are unsustainable. But China’s institution building in this area is still relatively lagging.
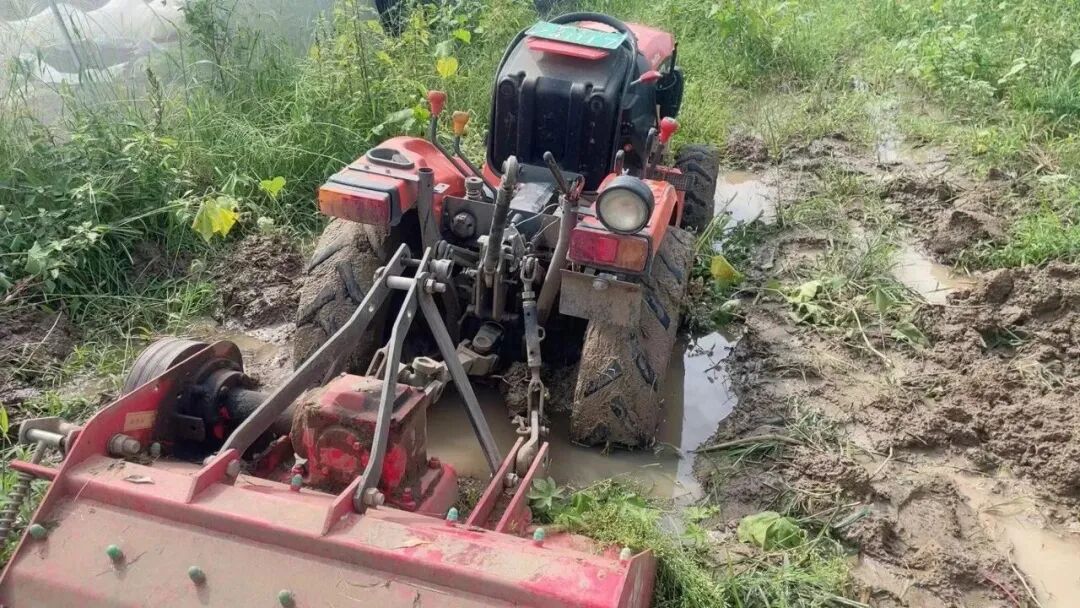
◉ A tractor stuck in the mud after rain, unable to move. Operating heavy machinery on arable land after rain can also compact the soil and damage the cultivated land. Image source: Xiao Liushu Farm
Climate Change Intensifies Claims Pressure
Q
You mentioned earlier that the net profit margin for agricultural insurance had once been 10%, which sounds quite profitable.
Yi Fujin: It sounds quite profitable, and indeed it is quite profitable. This is because the overall risk of China’s major agricultural products—that is, staple crops—is relatively controllable. Although disasters have been intensifying year after year, food security levels continue to improve, and successive years of increased output and good harvests mean that, on the whole, disasters affecting farmers’ agricultural grain production are controllable. Against this backdrop, and with smallholder farmers taking out insurance and settling claims collectively, insurance companies have saved a great deal in costs. As a result, for a fairly long period, the average profit margin of the agricultural insurance business was about 9%.
The issue is not that the profit margin is too high, nor that insurance companies should not earn this money, but what this money actually is. On the books, it is of course shown as profit. But if one takes into account the great variation from year to year in the frequency and intensity of disasters in agricultural insurance itself, the situation is different. Taking the United States, where agricultural insurance is the most developed and also began the earliest, as an example, the loss ratio in extreme years can reach 160%, 170%, or even 200%. This would be even more unimaginable in the motor insurance industry, but such a problem can arise in agricultural insurance. Once a huge disaster strikes, for example in 2022, when the region south of the Yangtze River went without rainfall for more than half a year, if payouts were truly made according to actual losses, the loss ratio would not fall below 200%, and this is perfectly normal.
Therefore, this surplus on the books of many insurance companies can be described both as profit and as a risk reserve used to cope with future catastrophe risk.
But at present, a catastrophe risk protection system has not yet been established, and the government is still very behind in formulating relevant policies. In addition, this money is actually the result of insurance companies benefiting from cooperation with the government. Through cooperation with the government, the government bears the cost, but the profit becomes that of the insurance companies. When this cost surplus turns into on-the-books profit for insurance companies, in the future it should be well pooled at the national and provincial levels in the form of a catastrophe risk reserve or a management fund. As for the accounting of insurance companies, a corresponding adjustment process will also be needed in the future.
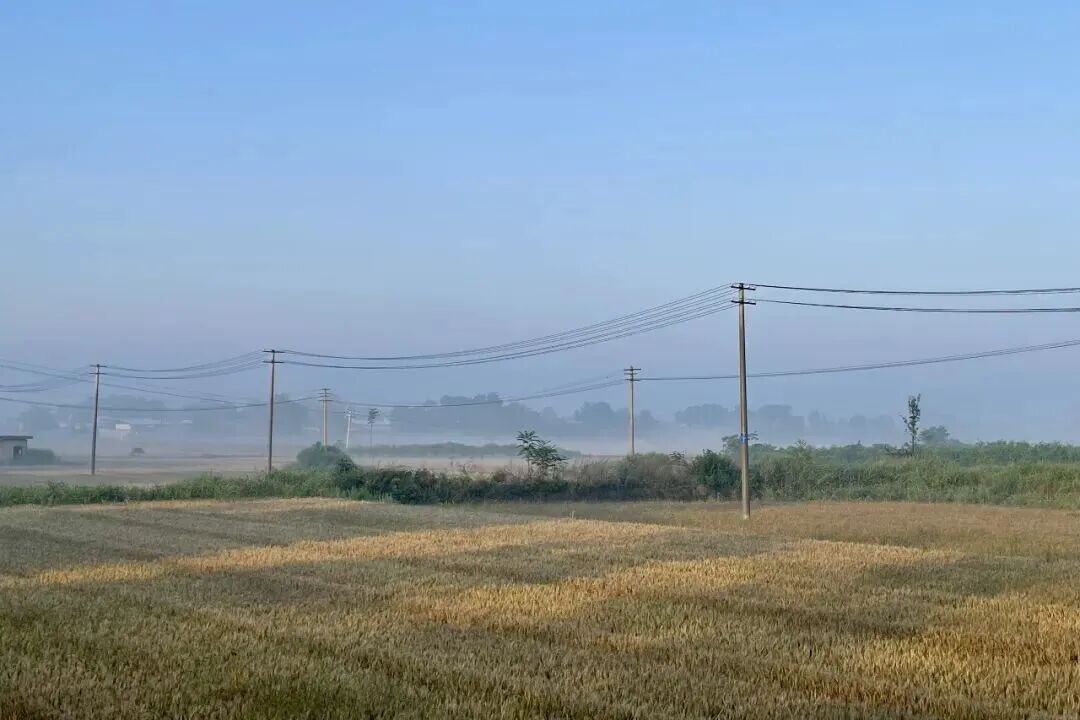
◉ In 2023, the Guanzhong region of Shaanxi experienced 10 consecutive days of “harvest-ruining rain”, and some of the wheat developed mould. Image source: Lü Wo Farm
Q
Actually, you also mentioned earlier that insurance companies’ profitability has declined over the past few years. As I recall, the profit margin you mentioned at the time is now 3–5%. What is the reason for that?
Yi Fujin: The profit margin may not be that low, but overall it is still relatively high. However, many factors have jointly contributed to this process.
First, as climate change makes extreme weather increasingly frequent, the pressure on insurance companies to settle claims is indeed rising steadily.
Second, the government has also recognised that insurance companies’ average profit margin is indeed very high. This is fiscal funding: local governments are putting out real money to provide premium subsidies, especially in areas where insurance is not deeply understood, and they demand that, for example, if the fiscal allocation is RMB 50 million, at least that amount be spent by the end of the year. For local governments this is a good thing, because the money yields results within the same year and is paid out to farmers. But when a major disaster really does occur, problems will arise.
Third, farmers’ awareness of defending their rights is strengthening, which has placed significant pressure on the compliance of insurance companies’ operations. Of course, this may also involve moral hazard. When we conducted field research in Henan and Anhui last year, we encountered this problem: some farmers felt that a payout of RMB 80 or RMB 90 from the insurance companies was not enough and demanded to be paid at least RMB 500 or RMB 600, because the cap is RMB 1,000. But given the insurance companies’ ability to settle claims, it is simply impossible to pay.
Fourth, in recent years, under increasingly strict regulation, insurance companies have also paid out as much as possible.
These four factors together account for the decline in the profit margin now being observed. Is a falling profit margin a good thing or a bad one? From a personal standpoint, I do not think it is necessarily a good thing. Because a major disaster risk management fund has not yet been established, once a major disaster strikes, the insurance companies’ ability to settle claims is greatly weakened. Therefore, a falling profit margin is, of course, a good thing from the farmers’ perspective, but it is also a dangerous signal.
Q
So, what is the current state of our risk reserve pool, and how much funding can be mobilised? Do you know?
Yi Fujin: I do not have a complete grasp of this data, but from what I have gathered indirectly, it is not particularly high and may even have fallen somewhat. In some countries, such as Japan, the accumulation of risk funds has reached 1.6 times premium income, used to cope with extreme disasters. But China is far from reaching this level.
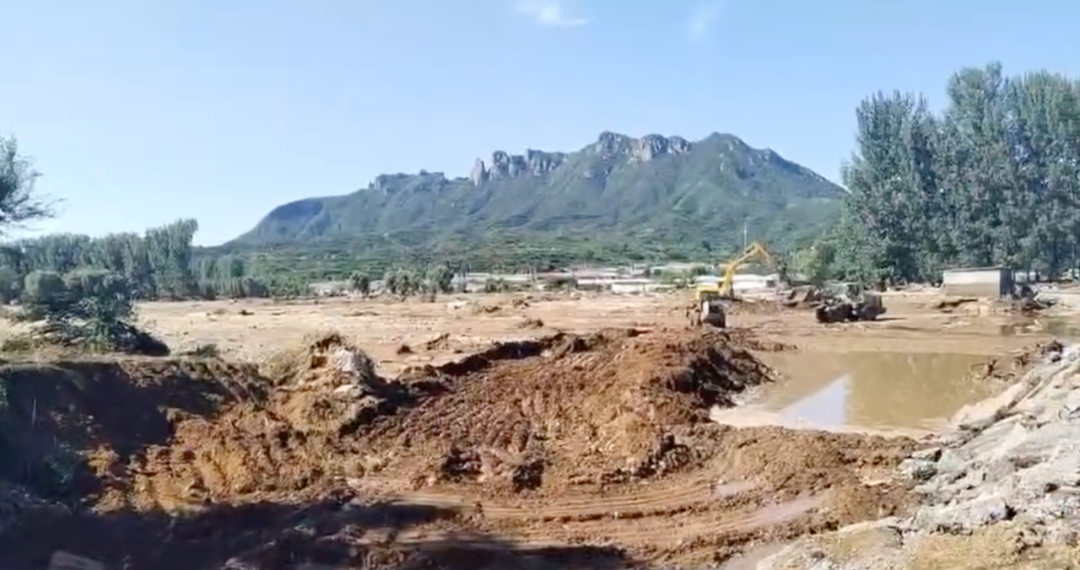
◉ In July 2025, extraordinary torrential rain again struck Beijing. On the banks of the Qingshui River in Beizhuang Town, Miyun District, at Sohu Farm, all 450 mu of land were swallowed up by the floodwaters. The flood almost erased every trace of the farm, leaving only washed-out roadbeds, waterlogged mud and a small amount of construction debris. Image source: Zhen Rui
Q
80% of the money for agricultural insurance comes from fiscal subsidies. China used to go through a stage in which agricultural insurance was run purely on a market-based basis, but that failed, and it later became policy-based insurance. From the current situation, is it possible to move agricultural insurance away from fiscal subsidies?
Yi Fujin: Indeed, from 1982 to 2004, this entire period was commercialised. The logic of complete marketisation failed. This is not a case unique to China; worldwide, no government has been able to get agricultural insurance up and running, and a very important reason is that agricultural risk is too high. On the supply side, the costs of agricultural insurance are also too high. On some occasions, I have half-jokingly said that although agricultural insurance is run by commercial institutions, its coverage in every part of the country is second only to that of the national government, and it can basically ensure that each township has a dedicated insurance company staff member. It has to bear the costs of institutional staff, transport and some technical means; these costs added together are very high. High costs also mean that agricultural insurance is not a good business. Overall, the marketisation of agricultural insurance, without government support—whether financial or administrative—is not feasible in practice; no successful cases have been seen worldwide.
Q
When I was in Henan, I met some farmers who actually had doubts about the insurance companies’ ability to settle claims. But they felt that the local fiscal situation was not good, that the local government itself was stretched for funds and simply unable to provide them with any security. So, does the local fiscal position play a role in the claims settlement process?
Yi Fujin: There is also an element of farmers’ guesswork here. The current poor state of local finances means that insurance cannot play its proper risk-protection role, mainly because of the particular logic of fiscal subsidies in China.
Our current subsidy logic is that, once the insurance company has collected 20% of the premium from farmers, the county-level government provides a matching contribution of 5% to 10% of the premium. Once this matching fund is in place, the fiscal subsidy process then moves up to the prefecture-level city, then to the provincial level, and finally to the central Ministry of Finance; the central fiscal subsidy can be disbursed only after the subsidies of the three lower-level governments have all been put in place. This has led to the so-called premium receivable problem. Particularly in the central and western regions, where local finances are tight, local governments cannot afford the funds. So, from the source of insurance enrolment, although farmers may already have paid, if local governments cannot produce the funds, the entire insurance chain breaks down and the insurance enrolment has not actually been completed. This is currently a very big problem. If local finances are tight and insurance has not even completed the contract-signing process, how can there be any talk of claims settlement?
Recently we saw a data point: the central government has actually earmarked roughly RMB 50 to 60 billion in budgetary funds. But in fact, since 2024, the completion rate of central fiscal subsidies has not reached 100%. The most important reason is that local governments cannot come up with the funds at source to help farmers pay premiums, so the central government’s funds cannot be put in place either. This is currently a very prominent problem.
But from the perspective of implementing insurance, local governments remain extremely important. Without the backing of township governments or village collective organisations, smallholder farmers would simply be unable to take part in agricultural insurance projects.
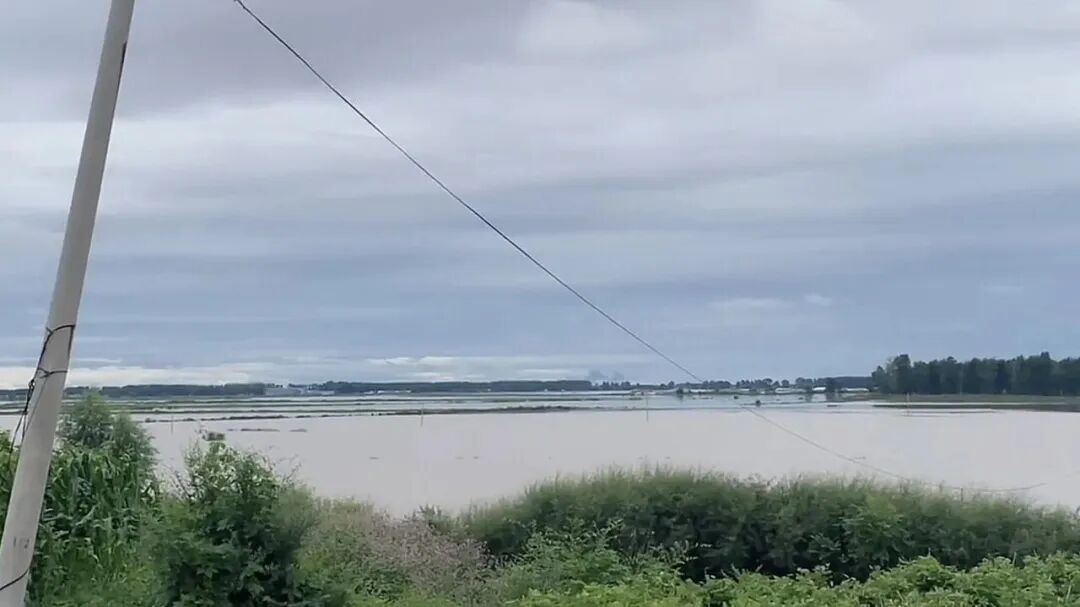
◉ In early August 2023, Wuchang in Heilongjiang was hit by rare torrential rain and flooding, with about 40% of the local 2.5 million mu of farmland submerged. The area shown in the image was originally a rice paddy and was entirely submerged under the floodwaters. Image source: Yvonne
Agricultural Insurance Is the Risk Consideration Paid for Food Security
Q
I recently came across the view that taking out agricultural insurance is a model in which money is paid out only after something goes wrong. The future direction should be to make disasters less frequent, with the sense that disaster prevention and mitigation are more important than paying out compensation. But is it possible for agricultural insurance to change from after-the-event insurance to pre-event disaster prevention?
Yi Fujin: When confronted with relatively minor flooding or waterlogging, or with concentrated rainfall, insurance companies can indeed respond by providing farmers with things such as water pumps and drought-resistant varieties. But once an extreme disaster occurs, these measures are certainly of no use.
So, as a matter of logic, I do not disagree with this view. Pre-event prevention is very important and does work for some disasters. But for more serious disasters, pre-event prevention is actually of little use.
The most fundamental question is: what exactly is the positioning of agricultural insurance?
If it is positioned as pre-event prevention, current financial management rules do not permit it either. In conversations with some friends in the industry, I have learned that 20% of insurance payout funds or premium funds is administrative expense, and only a portion of that 20% can be drawn out as prevention funds; the other 80% of the premiums cannot be used for prevention.
In any case, if one wants to use agricultural insurance to replace more effective measures such as the construction of farmland irrigation and drainage infrastructure, improvements in production technology, and the development of high-standard farmland, it would clearly put the secondary before the primary. Therefore, the division of roles and positioning of agricultural insurance within China’s entire agricultural policy system are very critical.
I have heard many versions of this. The vast majority of scholars, government officials and insurance company practitioners would regard the government’s premium subsidies for agricultural insurance as support for agriculture or support for farmers to carry out risk management. By conventional logic, that is indeed the case.
But there is another issue. When viewing agriculture, and in particular grain crop production, from a higher vantage point, and looking at it from society as a whole, an ample supply of grain—food security—is the cornerstone of social stability and development; it is a public good. Everyone can benefit from food security. In ordinary years of good harvest, consumers can buy enough grain from the market and enjoy the benefits that food security brings. But when grain output falls, the state carries out macroeconomic regulation, releases grain from state reserves to stabilise prices, and uses imports to adjust domestic grain supply. Consumers do not suffer much loss, but farmers, because food security is a national strategy, bear the losses, and no one pays farmers the corresponding premium, or at least some compensation.
In other words, in the process of achieving the strategic goal of food security, society as a whole has enjoyed the benefits of an ample supply of grain, but we have not paid the corresponding risk consideration for the risk of reduced grain output.
So, from this perspective, the government’s premium subsidies for agricultural insurance are not subsidies, but the risk consideration that the government should pay in order to achieve food security.
Looking at China’s more than a thousand years of history, the so-called “cheap grain harms farmers”—when production increases, farmers do not benefit because prices fall; yet, after production falls, due to the state’s effective grain price regulation, farmers also suffer losses. Considering these two things together, farmers actually bear all the losses, while society shares in the market returns; this is inequitable. In other words, returns and risks do not match at all. So the government should take measures to help farmers with risk management, so that low risk and low returns can be matched. From the perspectives of risk management and social equity, it is absolutely right for the government to pay this amount.
– This is Foodthink’s original article No. 817 –
Foodthink
Guest:
Yi Fujin
Qishu Distinguished Professor at Zhejiang University, Director of the Research Centre for Agricultural Risk Management and Safety Development at Zhejiang University, with long-term research on agricultural risk management and agricultural insurance policy issues.
Interview and compilation: Xiaodan
Editing: Yuyang, Tianle
Layout: Xiaoshu
Scan the code to tip and support original food knowledge
▼
▼
Click the image to read related articles
▼
Click a keyword to access more article collections
Seeds | Agricultural technology | Policy | Fermentation | Nutrition | Fruit | Fisheries | Activities | Recruitment | Food delivery | Wet market | Livestock farming | Food Talk | Sharing sessions | Book clubs | Harvest Festival | Smallholder farmers’ stories | Climate change | Rural development | Cooperative economy | Urban farmers | Food safety | Digital technology | Biodiversity | Pandemic and food | False solutions | Lianhe Creative Project | Ecological Agriculture Internship Programme
Beijing | Hebei | Shanghai | Guangdong | Guangxi | Henan | Sichuan | Jiangxi | Xinjiang | Shaanxi | Hong Kong | Chongqing | Zhejiang | Jiangsu | Guizhou | Northeast China | Taiwan | Inner Mongolia | Philippines | Canada | Russia | Mexico | Italy | United States | United Kingdom | Germany | Netherlands | Thailand | Sweden | Japan